

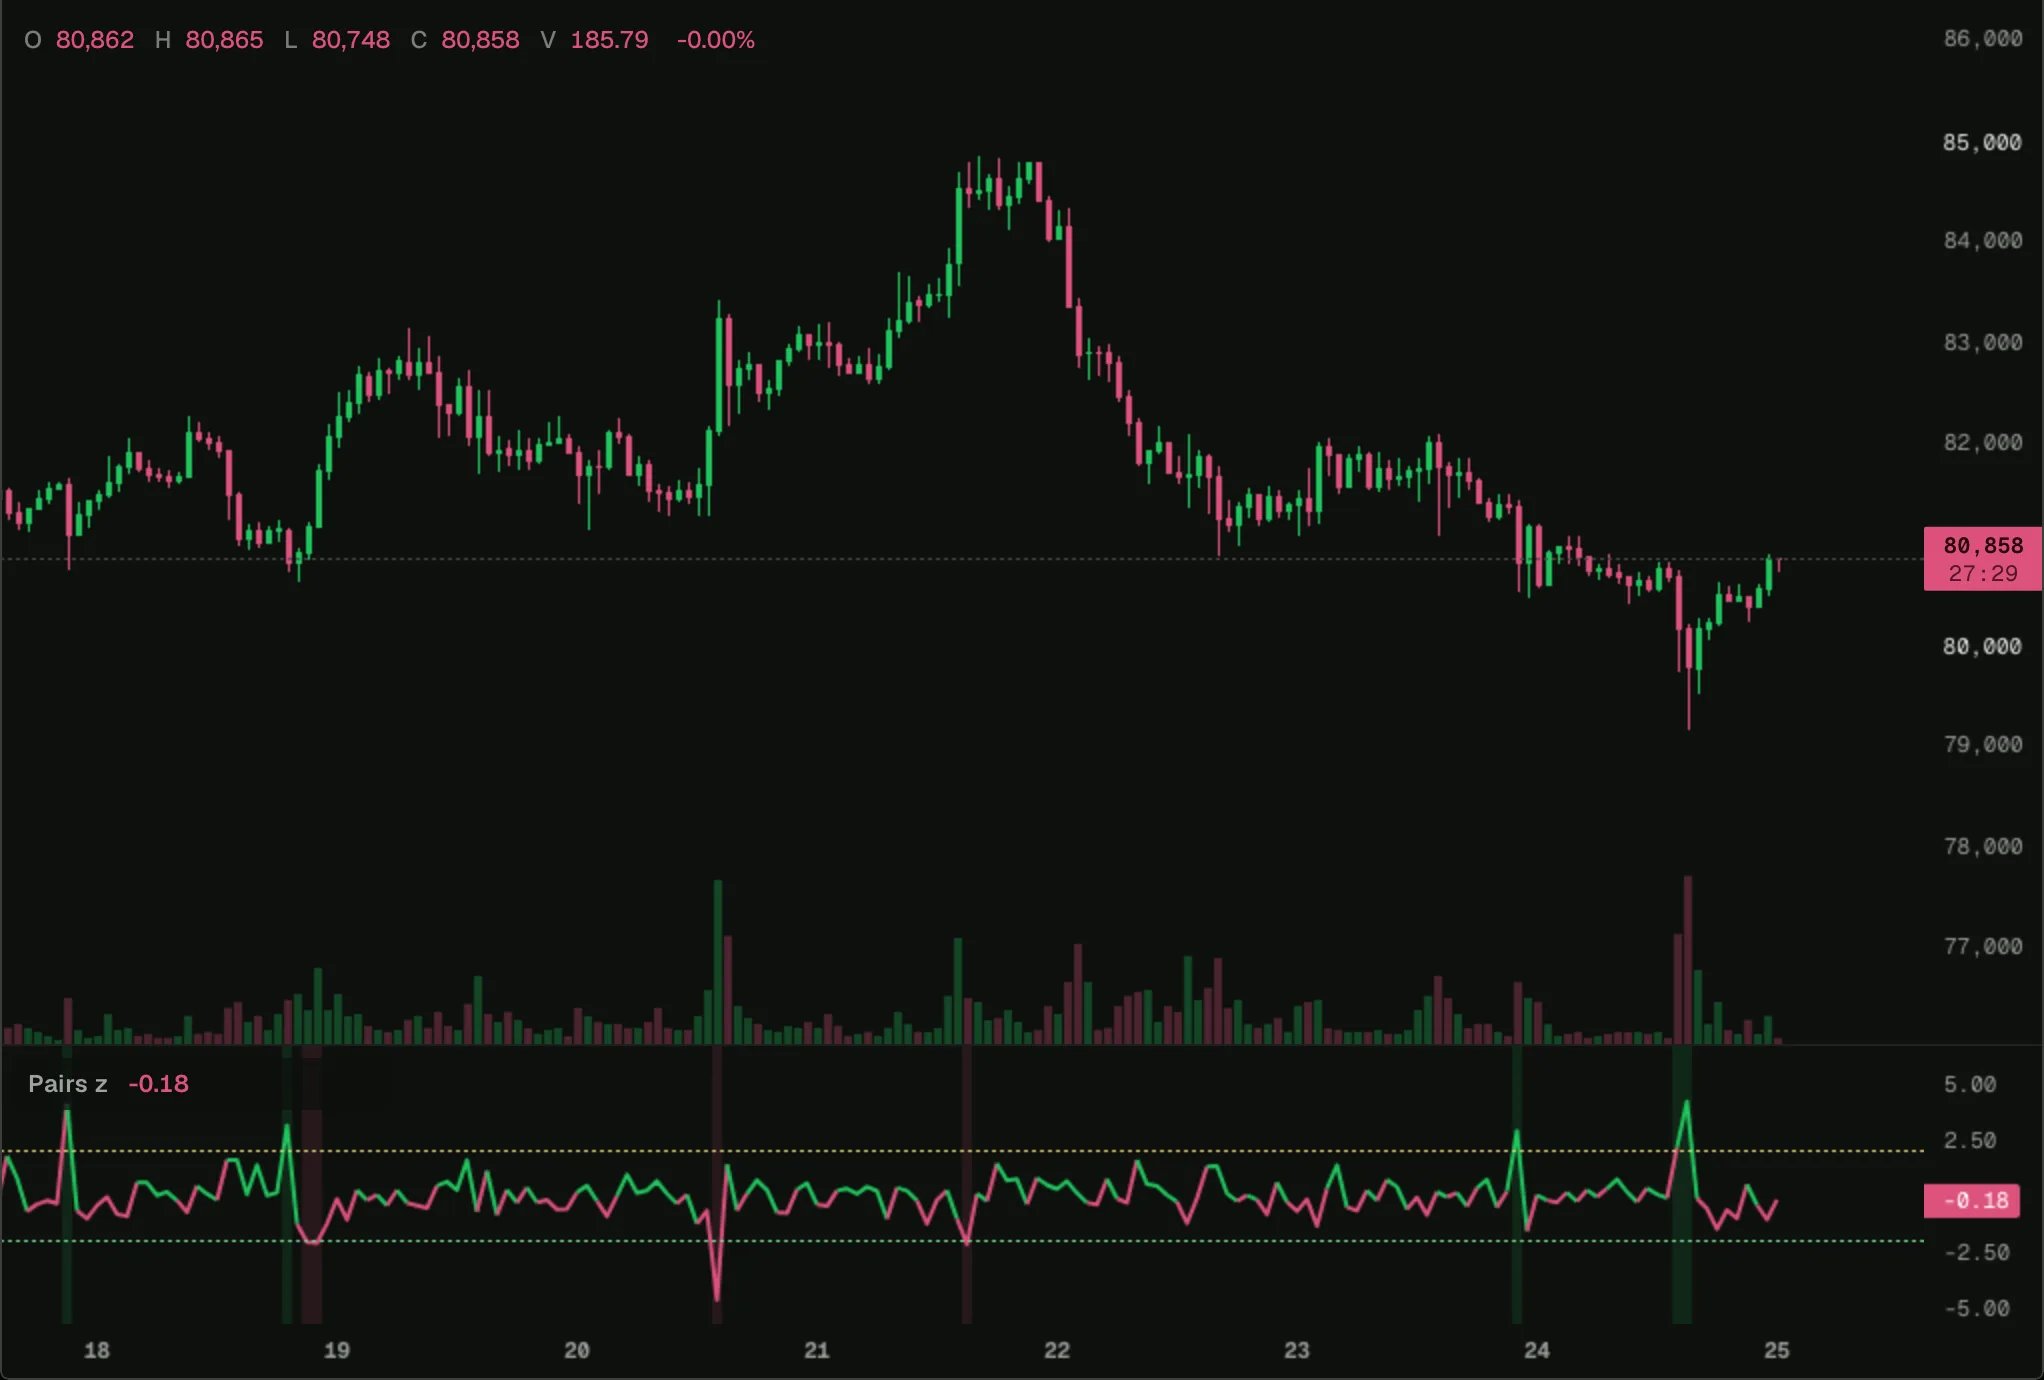
BTC on 1-hour bars in the 0xArchive Terminal, 2026-10-25.
Open on a chart
Load it on BTC 1h in the terminal, then change its settings or open it in the script editor.
How it works
ml.kalmanBeta treats the pair as y = α + βx with α and β drifting slowly, and updates both on every bar. Its spread is the bar’s surprise against the estimates from before the bar, so it never uses the bar to explain itself; stats.zscore puts it in standard deviations of its last 200 bars. (spreadZ scales it by the filter’s own noise setting instead, which suits daily bars at the default noiseVar and reads small on hourly ones.) Drift (delta) sets how fast the hedge ratio may move: larger follows the pair faster and leaves a flatter spread. The ratio itself is a hidden line, in the legend.
The script
kalman-pairs.ts